Your mortgage is a huge financial decision. It deserves the right kind of support.
I'm Dominic Piscopo, a CPA and licensed mortgage agent in Ontario. You get the same lender shopping any sharp broker does, plus a clear read on how the payment lands against your budget, your taxes, and your balance sheet five years out.
No cost to you on standard bank and prime-lender mortgages. The full explanation is further down.
A rough read on your price range
Household income, what you already owe monthly, and what you've saved - this estimates a purchase price using the same GDS/TDS ratios and stress test lenders actually apply. It's a starting point for a conversation, not a pre-approval.
How this is estimated
Lenders qualify you on two ratios: GDS (housing cost - mortgage payment, property tax, heat, and half of any condo fees - divided by gross income) and TDS (GDS plus all your other monthly debts, divided by gross income). This tool uses the standard limits of 39.0% GDS and 44.0% TDS.
You're not qualified at the rate you'd actually pay - lenders use the higher of your rate plus 2%, or 5.25% (the "stress test"). Whichever ratio runs out of room first sets your maximum mortgage at that stress-tested payment; price is that mortgage plus your down payment, adjusted for CMHC insurance if your down payment is under 20%.
Property tax and heat default to reasonable placeholders if you leave them blank - your actual numbers will differ by municipality and home type.
Not every lender fits every file
Rates get the headlines, but which lender will actually approve your file matters more. Broadly, there are three categories - here's who tends to land in each.
Banks, monolines, credit unions
The big banks, bank-only lenders (MCAP, First National, and similar), and most credit unions. The best rates available.
- Salaried or full-time work with 2+ years of history
- Credit that's generally in good standing
- Income that shows clearly on your tax return
- A standard down payment and debt ratios inside the usual limits
Self-employed can absolutely land here too, if two years of filed income supports the mortgage you're asking for.
Trust companies, specialty programs
Still fully regulated financial institutions (Home Trust, Equitable Bank, and alternative programs from some of the same monolines) - just not the big banks. Rates run higher than prime, usually with a one-time lender fee, and terms tend to be shorter.
- Self-employed income that's real but doesn't fully show on paper
- Credit that's rebuilding after a rough patch
- No established Canadian credit history yet
- Debt ratios a bit past what an A-lender allows
Often a one- or two-year bridge while the file gets cleaner, then a move back to a prime lender at renewal.
Not something I arrange
Individual investors and mortgage investment corporations (MICs), used for situations no institutional lender will touch - usually at a real cost in rate and fees.
My licence keeps my work to banks, trust companies, and other regulated institutions - the two categories to the left. If a situation ever genuinely needed a private lender, I'd tell you plainly and point you to someone licensed for it, rather than take the file myself.
Most people don't know which of these they'll land in until someone looks at the actual file. That's the conversation - not a guess from a rate table.
Your payment, and where you'll stand in five years
Enter the deal. You get the payment, the CMHC premium if one applies, and a payment-by-payment amortization for the length of a standard five-year term - interest, principal, and the balance you'd renew.
| Purchase price | $700,000 |
| Down payment15.0% of price | - $105,000 |
| Mortgage before insurance | $595,000 |
| Default-insurance premiumCMHC insurance, 2.80% of the mortgage, added to the loan | + $16,660 |
| Total mortgage | $611,660 |
*Assumes the home's value doesn't change - this is only the principal you've paid down plus your original down payment.
Where each year's payments go
Amortization schedule
| Year | Payments | Interest | Principal | Ending balance |
|---|---|---|---|---|
| Year 1 | $39,570 | $25,438 | $14,132 | $597,528 |
| Year 2 | $39,570 | $24,832 | $14,738 | $582,790 |
| Year 3 | $39,570 | $24,201 | $15,369 | $567,420 |
| Year 4 | $39,570 | $23,542 | $16,028 | $551,393 |
| Year 5 | $39,570 | $22,856 | $16,715 | $534,678 |
How this is calculated (and why it differs from a U.S. calculator)
Canadian fixed-rate mortgages are compounded semi-annually, not in advance - a legal convention, not a lender choice. This tool converts the annual rate to a per-payment rate with (1 + rate/2)^(2/n) - 1, where n is payments per year, then amortizes one period at a time.
The base payment is solved on a monthly schedule over the full amortization; bi-weekly and weekly options divide that figure across the year, and the accelerated options charge half the monthly payment every two weeks (or a quarter every week) - roughly one extra monthly payment a year, which is why the balance at renewal is lower.
Default-insurance premiums use current CMHC loan-to-value bands (0.60% up to 65% LTV, rising to 4.00% at 95%). Ontario charges 8% PST on the premium; that's paid in cash at closing and isn't added to the mortgage, so it's not in these numbers. Everything here is an estimate for planning, not an approval.
I work for you. The lender pays me.
Two things people are usually unsure about, answered plainly: whose side a broker is on, and what it costs.
I represent you, not the lender
As a licensed mortgage agent in Ontario I have a duty under the Mortgage Brokerages, Lenders and Administrators Act to recommend a mortgage that is suitable for you - not the one that pays the most, and not the one that closes the fastest for me.
In practice: I lay out the trade-offs between your options, I tell you plainly when an offer you already have (including from your own bank) is competitive and worth taking, and I put the recommendation and the reasoning in writing so you can check my work.
“Your job is to find me the right mortgage, not to sell me one.”
It doesn't cost you anything
The lender pays my brokerage a commission for putting your file together and bringing them borrowers who are the right fit for their products. It doesn't come out of your pocket, and it doesn't raise your rate.
Going through a broker also tends to get you a better rate than walking into a branch: brokerages negotiate volume discounts with lenders, and I'm comparing a large number of them at once rather than taking whatever single offer is on the table.
(The one exception is private lending, which can carry a broker fee. It doesn't apply to most people's situations, and I'd tell you well before it ever came up.)
Who you're working with
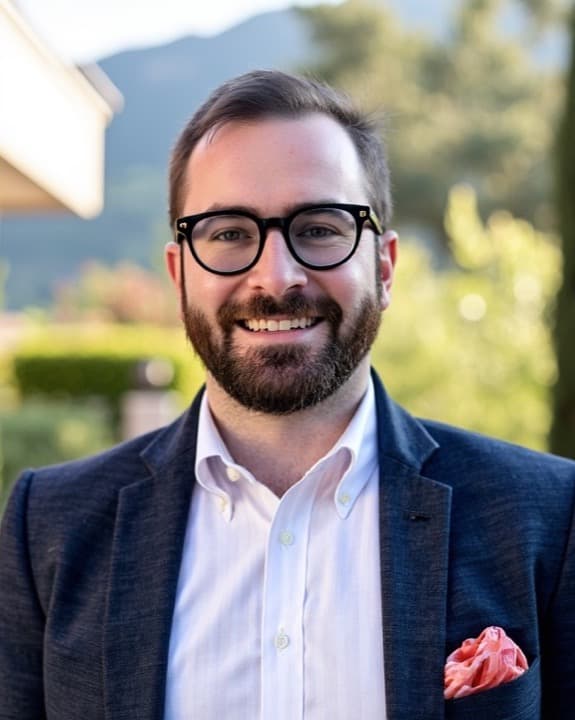
I'm Dominic Piscopo, a licensed mortgage agent (Level 1, FSRA #M26002079) with Smart Debt Mortgages (FSRA #12236), regulated by the Financial Services Regulatory Authority of Ontario. I'm also a licensed CPA.
I spent the early part of my career in tax, helping Canadians plan their taxes efficiently. After that I moved in-house, working alongside companies to make sure the financial decisions they were making were sound ones.
Here, I'm serving you as a mortgage broker, not as your accountant. But I bring all of that financial background to the table to help you make the best possible decision about your home.
Where that shows up:
- What the payment does to your monthly cash flow once every other commitment is in
- Whether a slightly higher rate with better prepayment terms is actually cheaper for your plans
- The tax treatment when part of the property is rented or used for a business
- What renewal looks like in five years under a few different rate scenarios
It's never too early to start
Where you are in the process changes what's useful to do, but not whether it's worth reaching out.
Even if you're just starting to look
If you're in the early stages of thinking about buying, I'm glad to have a conversation with no strings attached. We can work out what size of mortgage you could afford and likely qualify for, and I'll walk you through the whole process end to end so you know what's coming.
There's no obligation and nothing to sign. Plenty of people talk to me months before they're seriously shopping, and that's exactly the right time to do it.
The rate hold, and why about three months out matters
The one piece of real timing: once you have an accepted offer on a specific place, I can put a rate hold in place. Most major lenders will hold a rate for 90 to 120 days (some products are shorter), with no hard obligation to go ahead.
If rates rise before you close, you keep the held rate on a fixed mortgage. If rates fall, we can usually refresh the hold down to the lower rate. It only ever works in your favour, so it's worth having in place - which is why it's best to be talking to me by at least three months before your expected closing date.
Start the conversation
Send a note with roughly where you're at. No obligation, and no need to book anything - I'll reply by email, and if it's easier to talk it through we can set up a call from there.
Prefer to email directly? Reach out and mention roughly where you're at.
- dom@piscopomortgage.com
- Brokerage
- Smart Debt Mortgages
FSRA #12236 - Serving
- Ontario